

To read our full disclaimer, click here.
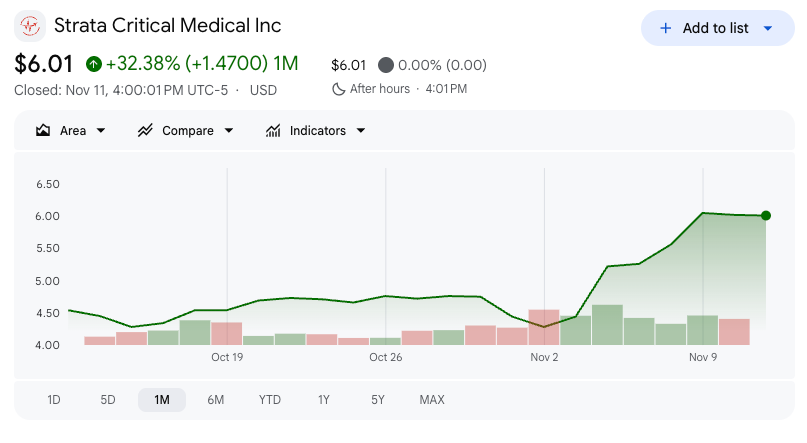
I wrote up Strata Critical Medical (NASDAQ: SRTA) at $4.34 in October.
Wednesday’s close was $6.01.
Up 38%.
Almost all of it came after the Q3 results on 3 November. The stock closed at $4.28 the day before and jumped 18% the day after.
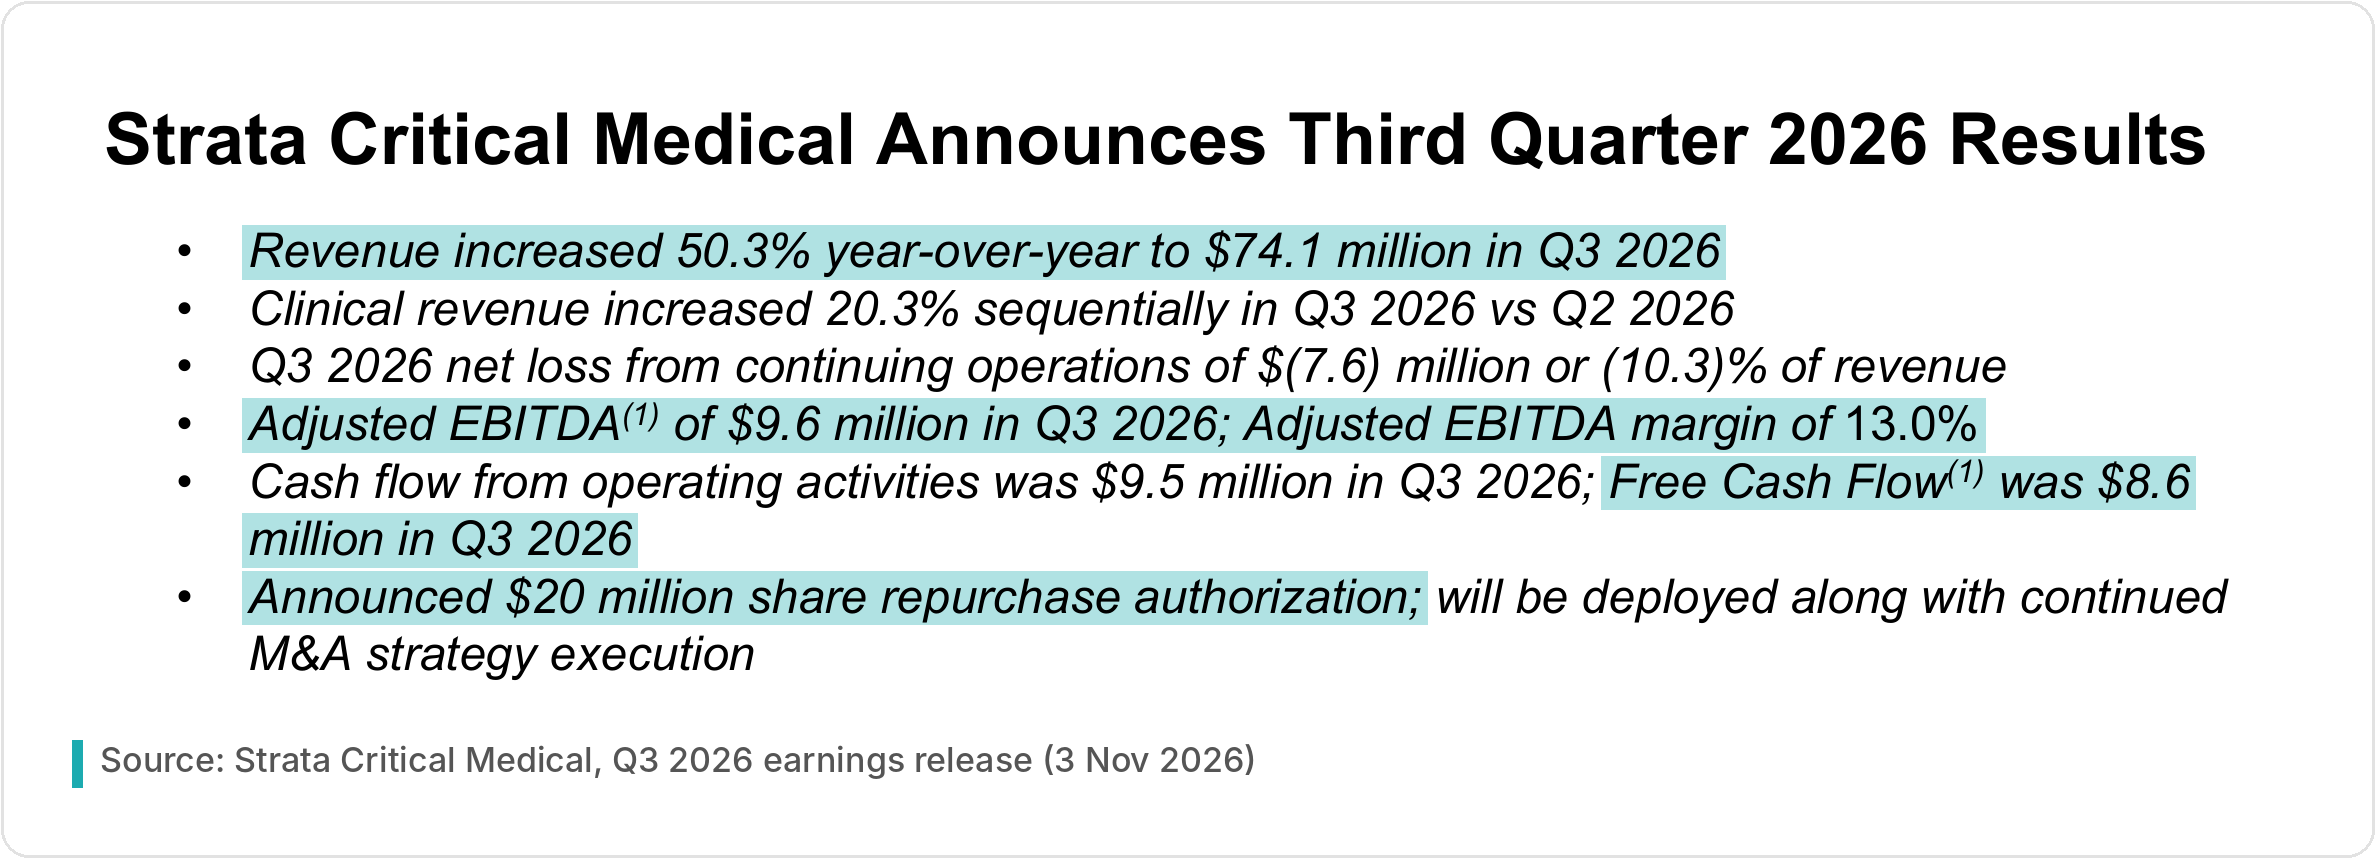
In five lines:
Revenue of $74.1 million, up 50% year-on-year, with Clinical up 20% on Q2
Adjusted EBITDA of $9.6 million at a 13.0% margin, against 8.5% a year ago
A record $8.6 million of free cash flow, three times Q2
Logistics gross margin back to 20.8%, a 2027 target reached a year early
A new $20 million buyback, with up to $27.5 million more Joby money due by Q1 2027
In October I said one line was the whole debate on this stock. Stock-based pay, running at roughly half of adjusted EBITDA.
This quarter it got worse.
Then management put a number on how much better it gets.
Below the paywall:
The stock comp line, and the cut management just guided to
Why trip distances went backwards, and why management doesn’t seem to mind
Clinical taking over as the growth engine
A new 80% NRP estimate, and the footnote under it
Third Point, four weeks on
The valuation after the move, with and without the equity cost
What I’m watching next
Here is everything you need to know…