

To read our full disclaimer, click here.
I first wrote up Eton Pharmaceuticals (NASDAQ: ETON) here at $16.92, on 11 November last year.
Monday’s close was $64.35.
Up 280%.
I put out my Q3 update on Eton on Multibagger Ideas yesterday. This is that update, here for Healthcare Stock Ideas readers who haven’t seen it.
The stock is up another 14% since it went out.
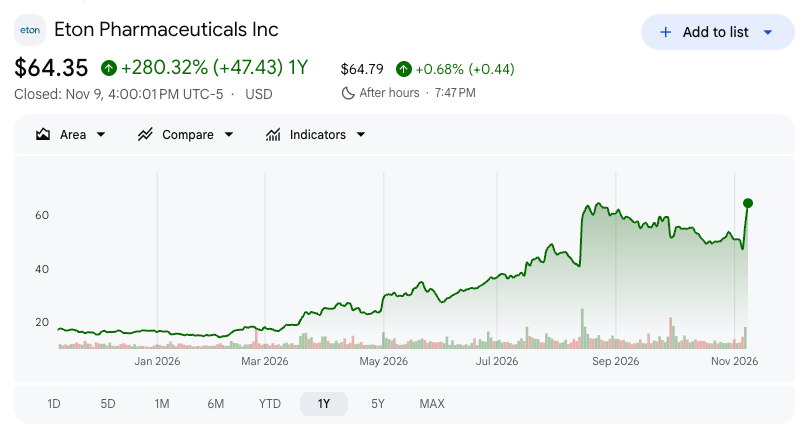
Eton put out its Q3 numbers after the bell on Thursday. In five lines:
Revenue of $57.9 million, up 158% year-on-year and 54% on Q2
Adjusted EBITDA margin of 49%, against 13% a year ago
A $200 million annual revenue run-rate, a goal set for the end of 2027, hit five quarters early
Full-year revenue guidance raised for the second quarter in a row, to more than $175 million
$35 million of operating cash flow in one quarter
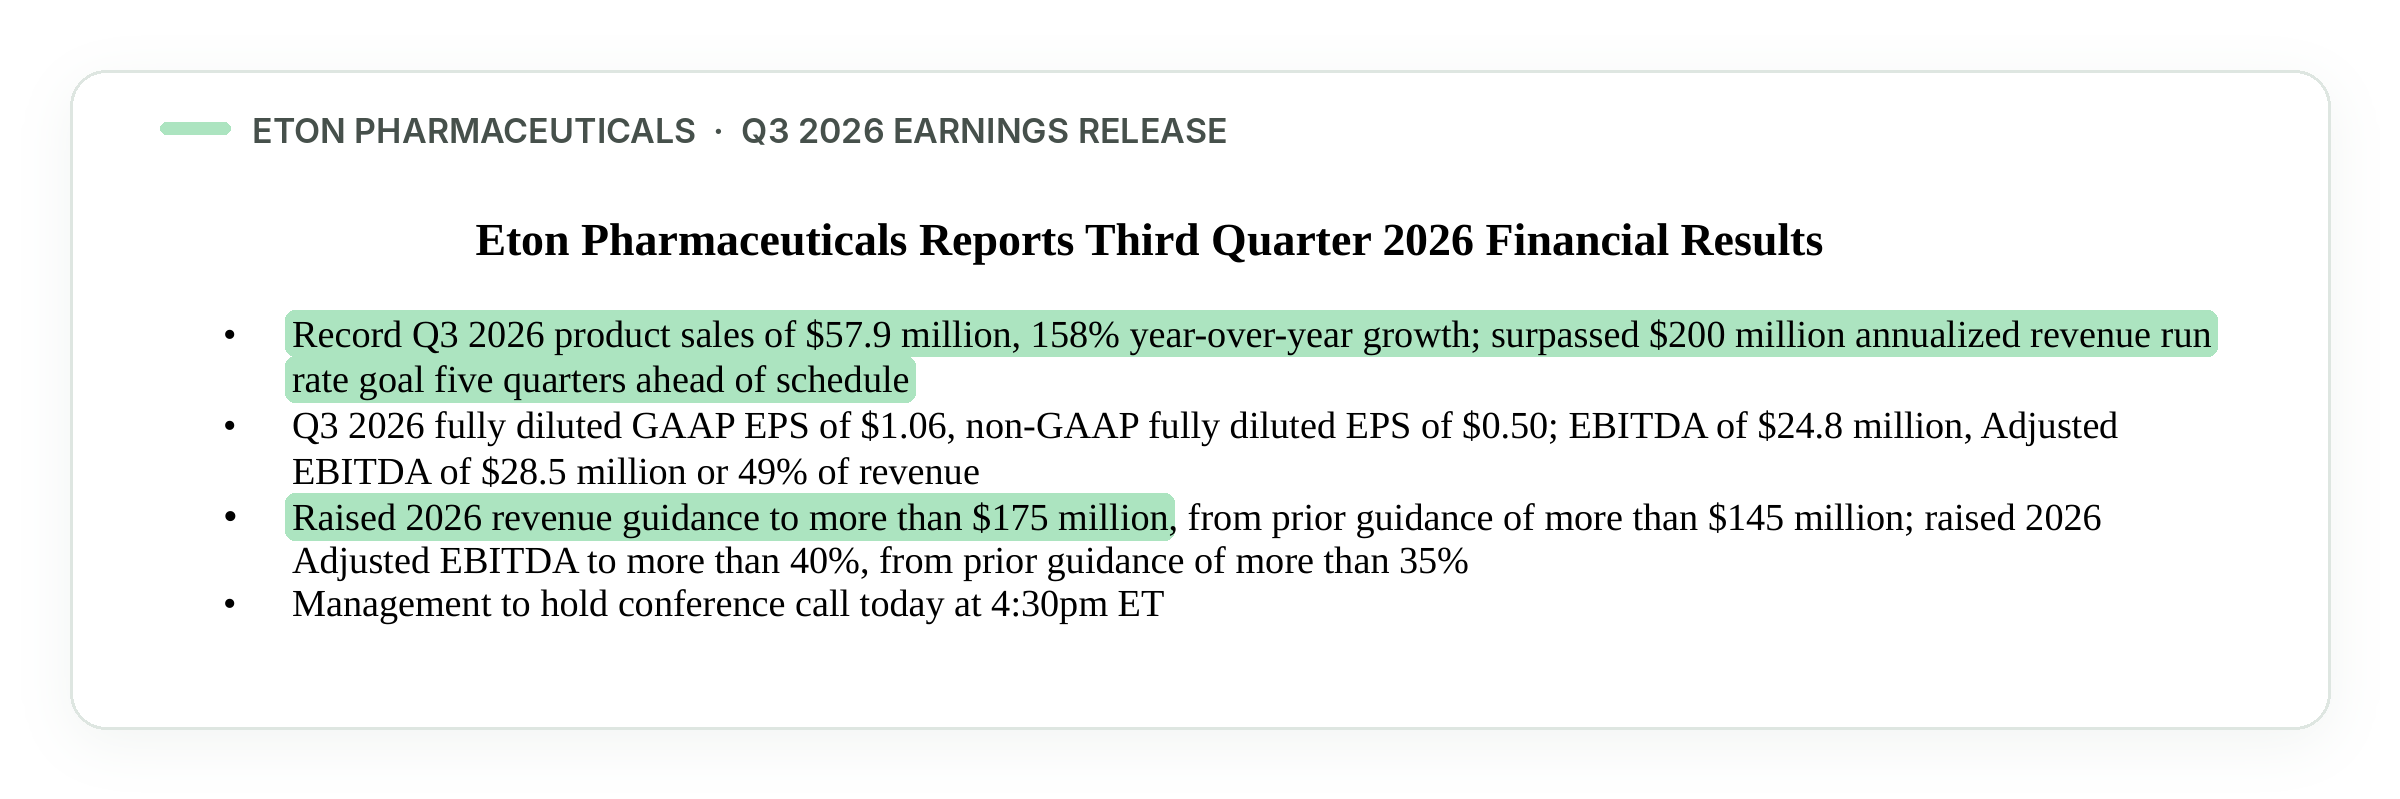
The share price is the weird part.
It closed at $58.86 the day after Q2 came out in August. By Thursday’s close, the evening of the Q3 release, it had slid 20% to $47.15. Friday took it back to $56.46, and Monday added another 14% to $64.35.
So over three months the stock is up 9%, and quarterly revenue is up 54%.
When I first wrote about Eton it was a $453 million company with eight products.
It now has twelve, another six in late-stage development, and it’s worth about $1.9 billion.
This is what I do across my pages.
I find companies nobody’s following, write them up early, and come back every quarter, bad results included.
Below the paywall:
How the biggest product did in its first full quarter
The pipeline result that didn’t go to plan
A new move into a $450 million market
The red flag from August, answered
What it’s worth once you count stock-based pay
What I’m watching next
It’s the most important quarter since I first wrote it up.
Here is everything you need to know…